How to Afford Braces, Glasses and Medical Bills on One Income
Parents are far more likely to carry health care debt than adults without kids. A 2022 KFF survey found 58% of parents had medical or dental debt compared to 35% of non-parents.That number made sense to me the moment I got a $4,550 quote for braces. One income. One parent. No second paycheck to absorb it.
This is the order I’d tackle it in. Insurance first, then tax-free accounts, then payment plans, then a dedicated savings pot. Programs and assistance come after that.
What Braces, Glasses and Medical Bills Actually Cost
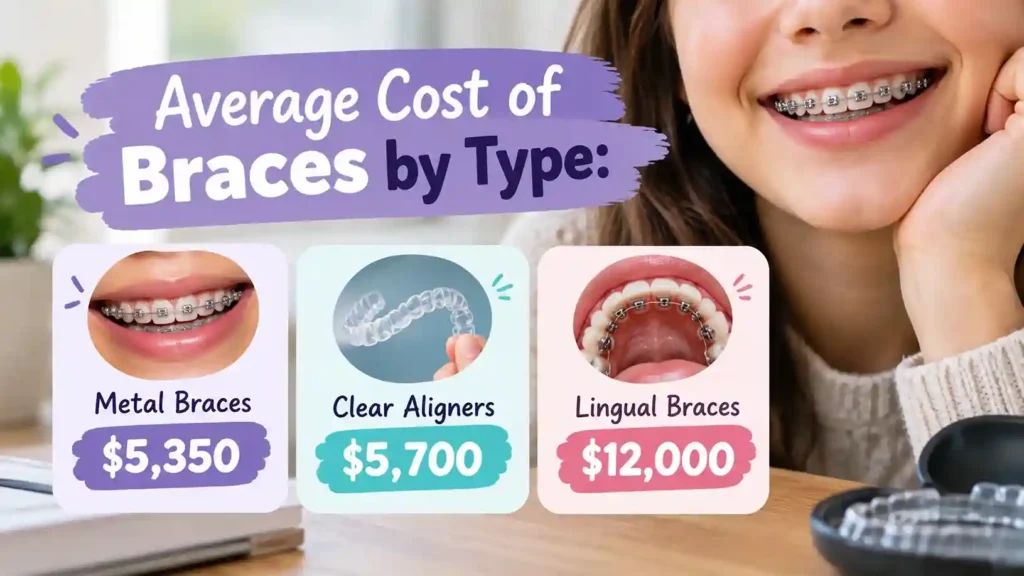
Braces vary a lot by type and case. One New York orthodontic practice puts the typical range at $3,000 to $8,000.
Colgate, citing Authority Dental, lists average prices at $5,350 for traditional metal braces and $5,700 for clear aligners. Lingual braces sit near $12,000.
Ask for a written estimate that lists everything. X-rays, adjustment visits and retainers should all be in that number not billed later.Glasses and surprise medical bills are harder to predict. That’s why the steps below work for all three.
Step 1: Call Your Insurance Before You Book Anything
Check your dental plan for orthodontic coverage. Many plans have a lifetime maximum for braces, often around $1,000 to $2,500 and often pay only about 50% up to that cap.
Some plans only cover children. Some have waiting periods. Ask both questions on the phone.Get the answers in writing or note the date and the rep’s name. Coverage disputes are easier to win with a record.
Step 2: Use an FSA or HSA (Time It Carefully)
Orthodontia is an eligible expense for a health care FSA, according to FSAFEDS. That means you pay with pre-tax dollars.
For plan years starting in 2026, the IRS limit on employee contributions to a health FSA is $3,400. The HSA limit is $4,400 for one person and $8,750 for a family.
Here’s the single-mom catch. A married couple can each open an FSA. You only get one.
FSAs are also mostly use-it-or-lose-it. Employers can allow a carryover of up to $680 in 2026, but not all do. Check your plan before you count on it.
If your treatment starts late in one plan year and runs into the next, you can draw from two years of contributions. Your savings depend on your tax bracket, so ask HR for a quick estimate.
Step 3: Ask for an In-House Payment Plan
Many orthodontists offer their own payment plans, sometimes with no interest. This usually beats third-party financing.One example from an orthodontic practice: on a $7,460 treatment plan, you might pay $500 down and $290 a month for 24 months. That’s the full amount with no added interest.
Always ask two questions. Is there interest? Is there a penalty if I pay it off early?
If the office only offers third-party financing like CareCredit, read the terms slowly. Ask specifically whether interest is deferred and what happens if you don’t pay the balance in full by the end of the promo period.
Step 4: Open a Separate Account for Kid Health Costs
This is the part most guides skip. Braces aren’t a surprise. Neither are glasses, which usually need replacing every year or two as prescriptions change.
A dedicated sinking fund turns a big scary quote into a monthly number. If you’re already splitting your money into buckets, this is a natural fourth one. Our guide to budgeting on one income shows where it fits.
Here’s how long it takes to save $4,550 at different monthly amounts:
| Monthly amount | Time to reach $4,550 |
|---|---|
| $50 | 91 months |
| $100 | 46 months |
| $200 | 23 months |
| $250 | 19 months |
Even if you can’t hit $250 a bigger down payment means a smaller monthly bill later. That matters more than saving the full amount.
Need help finding the first $50? Our list of ways to save money as a single mom has practical places to start.
Programs That Can Lower the Bill (US)
Start with Medicaid and CHIP if your income might qualify. States must provide dental benefits to children covered by Medicaid and CHIP, according to Medicaid.gov.
Federal rules also require Medicaid to cover eyeglasses for eligible children under 21 when medically necessary, under the EPSDT benefit. Braces are covered only when the state considers them medically necessary, so ask your state Medicaid office directly.
Smiles Change Lives is a nonprofit that matches low-income families with orthodontists who donate their time. Kids must be 7 to 18 with a moderate to severe need.
Families pay a $30 application fee and a $650 required investment per child. The nonprofit says average braces cost around $6,000 outside the program.
There are limits. Wait times can pass 12 months in some areas. And the $650 can’t be paid with an FSA or HSA.
If You’re in the UK
NHS orthodontic treatment is free for under 18s with a clear health need. Eligibility is assessed using a scoring system called IOTN and waiting lists can be long.
Adults usually pay privately. If your child doesn’t qualify or you can’t wait ask your dentist about private payment plans.
For glasses, the NHS gives optical vouchers to children under 16 and to 16 to 18 year olds in full-time education. Sight tests are free for under 16s.
How to Handle Surprise Medical Bills
Ask for an itemized bill before you pay anything. Errors happen, and you can’t dispute a total you can’t read.Ask if the provider has a financial assistance program. Nonprofit hospitals are required to have a written policy under IRS rules so it’s worth asking.
If you can’t pay in full ask for a payment plan before the bill goes to collections. It’s much easier to set one up early than to fix it afterward.
One more note on taxes. The IRS lets you deduct medical expenses above 7.5% of your adjusted gross income but only if you itemize. On one income, that often doesn’t apply, so check before counting on it.
Which Option Fits Where
| Option | Best for | Watch out for |
|---|---|---|
| Insurance | Any planned treatment | Lifetime caps and age limits |
| FSA or HSA | Big planned costs | Use-it-or-lose-it deadlines |
| In-house payment plan | Braces and aligners | Interest and prepayment penalties |
| Sinking fund | Recurring costs like glasses | Needs monthly discipline |
| Medicaid or CHIP | Low-income households | State rules vary |
| Nonprofit programs | Kids 7 to 18 | Long waitlists and a required fee |
What I’d Do First This Month
- Call your insurance and ask about orthodontic benefits, caps, and age limits.
- Ask HR what your FSA limit and carryover rules are.
- Get two written quotes from orthodontists, and ask about payment plans.
- Start a dedicated account even at $25 a month.
- Check Medicaid or CHIP eligibility if your income is tight.
You don’t need to solve all of it this month. You just need the first call.
If you want a place to track it our free budget planner printable has room for a health costs category.