The 3 Bank Accounts Every Single Mom Should Have (And Why)
Fifteen percent of single-parent households don’t have a bank account at all. That’s according to FDIC data and it’s almost four times the national average.
If you’ve got one account that everything runs through, checking, bills, groceries, the occasional emergency, you’re already ahead of a lot of people. But one account also means everything competes for the same dollars all the time.
I ran my whole life through a single checking account for the first year after my divorce. Rent came out, then groceries then whatever was left disappeared into “stuff.” I never knew if I actually had money or just hadn’t paid a bill yet.
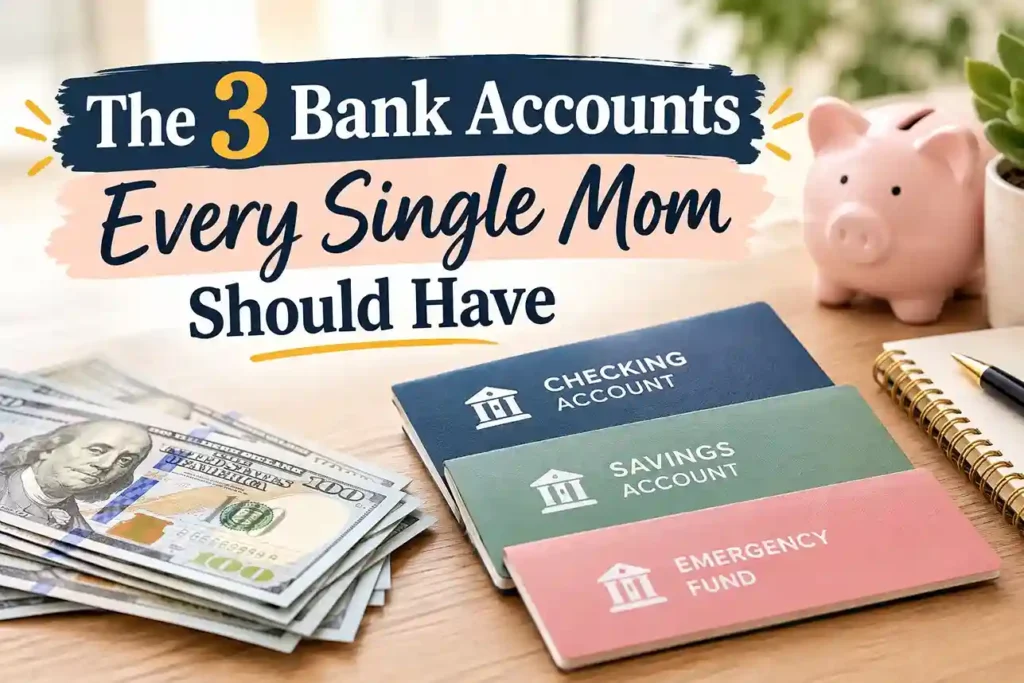
Splitting into three accounts fixed that. Not because three is a magic number but because each one does a job the others can’t.
Account 1: Your Primary Checking Account
This is where your paycheck lands and your bills leave from. Rent, utilities, phone, subscriptions, groceries. Nothing else touches this account.
The single biggest change I made here wasn’t opening a new account. It was turning on low-balance alerts. Most banks let you set a threshold and getting a text when you’re close to it beats finding out at the register.
If you’re building your budget around this account for the first time our guide to budgeting on one income walks through exactly what should flow through here versus what shouldn’t.
Account 2: Your Emergency Fund
This one is separate and it stays separate. Not linked to a debit card you carry around. Not the account you check when you’re deciding whether you can afford takeout.
Federal Reserve data from 2025 shows only 47% of parents living with kids under 18 have three months of expenses saved compared to 57% of adults without kids at home. That gap is real and it’s not because single parents aren’t trying. There’s simply less room in the budget to build it.
Start smaller than the “three months of expenses” advice you’ll see everywhere. FDIC research found 55% of single parents save for emergencies at all versus almost two-thirds of households overall. Getting into that first group matters more than hitting a specific number right away.
A realistic starting target: $500. Not because $500 solves everything but because it covers most of the small emergencies that actually show up, a car repair, a broken appliance, a copay you weren’t expecting.
Once that’s in place build toward one month of expenses, then three. Our free budget planner printable has a section built specifically for tracking this without needing a separate app.
Account 3: Your Sinking Fund (Not Just “Savings”)
Most advice stops at two accounts: checking and emergency fund. That’s not enough and here’s why.
An emergency fund is for the unexpected. But a lot of your biggest expenses aren’t unexpected at all. You know Christmas is coming. You know the school year starts in August. You know your kid’s birthday happens every single year, on the same date like clockwork.
A sinking fund is money you set aside gradually for a specific, planned cost. A little each month so the expense doesn’t hit as a single overwhelming withdrawal from your emergency fund or, worse, a credit card.
Here’s how the three accounts split by purpose:
| Account | Purpose | What comes out of it |
|---|---|---|
| Checking | Daily life | Rent, bills, groceries, regular spending |
| Emergency Fund | Unexpected | Car repair, medical bill, job loss gap |
| Sinking Fund | Planned but irregular | Holidays, school costs, birthdays, car registration |
If you don’t have $50 a month to split three ways right now, that’s fine. Start with $10 into the sinking fund and $10 into the emergency fund and adjust as you go. The habit matters more than the amount at first.
What This Actually Looks Like Month to Month
On payday money moves in this order. Bills and essentials stay in checking. A set amount even if it’s small, transfers to the emergency fund. Another set amount transfers to the sinking fund.
Automating these transfers matters more than the amount does. Our roundup of ways to save money as a single mom has specific tactics for finding that first $20-30 a month if your budget feels too tight to split right now.
You don’t need a perfect system on day one. You need three accounts that each know their job so your money stops competing with itself every time something unexpected or entirely predictable shows up.